
Would You Pay $240 Million for a Used Tanker?
VLCC asset values have entered territory that would have looked absurd only months ago. The question for a buyer is no longer whether today’s freight market is extraordinary. It is how long extraordinary earnings must last before an extraordinary purchase price starts to make sense.
Here’s a sentence that tells you almost everything about the tanker market in late 2026: a ship that already exists can cost dramatically more than a brand-new one.
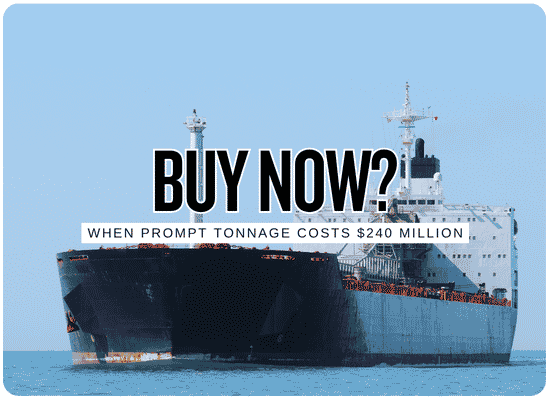
Current reporting has put a record prompt tanker resale around $240 million. Meanwhile, a five-year-old VLCC benchmark has been assessed around $207.6 million, nearly 49% above a roughly $139.6 million newbuilding benchmark. And this isn’t merely an index comparison: Scorpio Tankers announced on September 29 that it had contracted two scrubber-fitted 306,000-dwt VLCC newbuildings at $135 million each for delivery in September and October 2028.
In other words, today’s tanker buyer can potentially pay more than $200 million for a ship that is already several years old—or roughly $135 million for a brand-new ship it cannot have for another two years.
That difference is the entire trade. The market isn’t really paying $100 million extra for old steel. It is paying for time.
The headline needs one important qualification.
The reported $240 million figure is associated with the hottest end of the secondary market—modern/prompt resale tonnage—not the ordinary price for every five-year-old VLCC. The more representative five-year benchmark cited in current market reporting is around $207.6 million. Both numbers are extraordinary, but they describe different points on the asset curve.
The tanker price board has turned upside down
Normally, age costs money. Today, immediate availability is worth more.
Scorpio Tankers’ September 2026 Hengli VLCC order, with delivery scheduled for late 2028.
Current benchmark referenced alongside VesselsValue’s secondhand assessments.
Roughly $68 million above the cited $139.6 million newbuilding benchmark.
Record secondary-market level reported amid the current rush for tanker capacity.
| Asset | Indicative Price | Premium vs $139.6M NB | What Buyer Is Really Paying For |
|---|---|---|---|
| Newbuilding benchmark | $139.6M | — | New technology, fresh life—but delayed delivery. |
| 5-year-old VLCC | $207.6M | +$68.0M | Immediate earning capacity during an exceptionally strong market. |
| Prompt resale extreme | $240.0M | +$100.4M | Maximum scarcity premium for near-immediate availability. |
Why would anyone pay more for the used ship?
Because the cheaper ship does not arrive when the money is being made.
The used ship can earn tomorrow
A modern secondhand or resale VLCC can potentially enter employment almost immediately after closing, surveys and positioning. A newbuild ordered today may not arrive until 2028, 2029 or later.
Freight has become extraordinary
DHT reported on October 12 that roughly half its available Q4 VLCC spot days had already been booked at an average $509,100 per day. Some individual routes and fixtures have been considerably higher.
Trade disruption absorbs ships
Longer voyages, altered crude flows, security risks and inefficient routing all increase the number of ship-days required to move the same barrels.
Owners do not want to sell
When a ship can generate exceptional cash flow, the reservation price for its owner rises. A prospective buyer must often compensate the seller for giving up that earning machine.
The comparison is not really used versus new. It is earn today versus wait two or three years. That can justify a substantial secondhand premium. The difficult question is whether today’s premium has become larger than the earnings opportunity it is supposed to buy.
The $105 million question
Compare the $240M resale extreme with an actual $135M newbuilding contract.
The simplest stress test asks whether exceptional near-term earnings can repay that $105 million before freight returns to a more ordinary level.
For the calculations below, I use $75,000/day as an illustrative normalized TCE assumption. That is not a forecast. It is a useful real-world anchor because DHT fixed a 2015-built VLCC for three years at $75,000/day earlier in 2026.
The calculation then asks: how much must the vessel earn above $75,000/day during the boom window to recover the $105 million purchase premium?
If the market normalizes in six months
The buyer needs a truly extraordinary six months.
Add the illustrative $75,000 normalized TCE and the vessel needs roughly $650,000/day during that six-month window to earn back the full premium purely from abnormal earnings.
DHT’s current Q4 spot bookings of roughly $509,100/day are astonishing, but even that level does not fully clear a $105 million premium in only six months under this conservative test.
If the market normalizes in twelve months
Add a $75,000/day normalization assumption and the required average TCE becomes roughly $363,000/day.
This is where today’s purchase price starts looking less impossible. If a ship actually averaged something close to today’s half-million-dollar earnings for a full year, the availability premium could theoretically be earned back surprisingly quickly.
The problem is embedded in that sentence: for a full year.
If the market stays exceptional for two years
Add the illustrative $75,000 normalized TCE and the required average falls to roughly $219,000/day.
At that point the economics look considerably more defensible. But a buyer making this assumption is effectively betting that tanker disruption, long-haul trade and vessel scarcity remain strong through much of the period when today’s large VLCC orderbook begins moving toward delivery.
Required average TCE to recover the $105M premium above a $75K/day normalized assumption.
Still an extremely strong market, but below current DHT spot bookings.
Much easier mathematically—but requires the exceptional cycle to last.
The five-year-old ship produces a different answer
The $207.6M benchmark carries a smaller—but still remarkable—premium.
Using the cited $139.6 million newbuilding benchmark, a $207.6 million five-year-old VLCC carries a premium of about $68 million.
| Normalization Window | Premium | Extra Earnings Needed / Day | Required TCE With $75K Baseline |
|---|---|---|---|
| 6 months | $68M | $372,600/day | ≈ $447,600/day |
| 12 months | $68M | $186,300/day | ≈ $261,300/day |
| 24 months | $68M | $93,200/day | ≈ $168,200/day |
At DHT’s current roughly $509,100/day spot-booking level, the theoretical $68 million premium over a $75,000/day normalization assumption could be recovered in only about five months if those earnings were maintained continuously. That is the seductive math behind today’s asset prices.
But look how fast the earnings number moves
One quarter can completely change the acquisition thesis.
This is the danger of valuing a 20-year asset from a 20-day freight market. A buyer can be completely correct that today’s rate is real and still be completely wrong about the vessel’s value if that rate proves temporary.
The hidden second bet: what happens to the ship’s value?
Earnings payback is only half the acquisition model.
Suppose somebody pays $240 million and earns extraordinary money for the next year. If tanker freight then normalizes and the same vessel is suddenly worth $170 million, the owner may have produced huge operating cash flow while simultaneously losing $70 million of asset value on paper.
That may still be a perfectly successful transaction—but only if the buyer modeled both sides.
Earnings upside
Every day above normal TCE helps amortize the prompt-availability premium.
Asset-value downside
When scarcity disappears, depreciation can reappear very quickly. A five-year-old vessel eventually has to become worth less than a brand-new vessel again.
Age keeps moving
The secondhand ship is not frozen at five years old. By the time a 2028 newbuild arrives, today’s five-year-old vessel may be seven or eight years old.
Newbuild payments are staged
A $135 million shipyard contract generally does not require the owner to commit the entire price as cash on day one. A prompt acquisition normally puts far more capital to work immediately.
The orderbook is the giant number behind the giant price
A lot of ships are coming.
Owners have responded aggressively to the freight boom. Veson reported VLCC ordering up roughly 358% year over year and the orderbook at approximately 38% of the existing fleet.
Reuters separately reported in September that more than 217 VLCCs had been commissioned during 2026, representing more than $20 billion of investment, with deliveries extending as far out as 2030.
There are good reasons not to translate that directly into a future glut. A meaningful share of the existing VLCC fleet is old, replacement demand is real, and future trading inefficiency could continue absorbing ships.
But anyone paying $200 million-plus for prompt tonnage should at least ask the uncomfortable question: what will the secondhand scarcity premium look like when hundreds of newly ordered ships begin entering the fleet?
Waiting for a newbuild is not free either
The newbuilding comparison has its own trap.
Saying “why pay $240 million when a new ship costs $135 million?” sounds obvious until the buyer asks when that new ship will actually be delivered. Scorpio’s latest $135 million VLCCs are scheduled for September and October 2028. Other current orders extend into 2029 and 2030.
If a prompt vessel earns $250,000/day for two years while the ordered newbuild sits on a construction schedule, that is roughly $182.5 million of gross TCE opportunity before operating expenses, off-hire and other costs. Suddenly, paying a large prompt premium is not irrational.
The danger is paying the full value of those future earnings in advance and then discovering they were never future earnings at all—they were a six-month spike.
Who could rationally pay $240 million?
Capacity may be strategic
The buyer may value guaranteed transportation capacity more highly than a pure ship investor evaluating only residual value and TCE.
Freight is part of the commodity trade
Owning tonnage can preserve arbitrage opportunities or physical flows that become uneconomic when third-party freight is scarce.
Existing commercial platform
A large owner may already have cargo relationships, financing and operating infrastructure capable of monetizing prompt tonnage rapidly.
Fleet economics matter
One expensive acquisition may be supported by older low-basis ships already generating large cash flow.
This is the dangerous one
A buyer relying mainly on current spot rates and future resale value has the least margin for error if the freight cycle reverses.
Lock the economics first
Long period coverage at unusually high rates can turn an alarming asset price into a much more measurable investment case.
The ten questions I would ask before paying today’s price
Five red flags in a $200 million-plus tanker model
Would I pay $240 million?
At current VLCC earnings, the number is not automatically insane. That is the remarkable part.
If a prompt vessel genuinely earns around today’s exceptionally high rates for long enough, $100 million of premium can be absorbed far faster than most ship buyers would normally imagine. A five-year-old vessel carrying a smaller $68 million premium can theoretically amortize that premium in only months at current spot earnings.
But the buyer is making two bets simultaneously: that the freight boom lasts long enough to earn back the premium, and that the vessel’s residual value does not collapse faster than those earnings accumulate.
A $135 million newbuild lets you wait for the future. A $240 million prompt tanker lets you monetize today. The buyer paying the extra $105 million is effectively putting a very large price on one thing: how long “today” lasts.
Research basis
[1] Barron’s / ANZ — October 12, 2026. Record tanker freight conditions and reported $240 million secondary-market tanker price.
[2] VesselsValue market assessments cited in current shipping-market reporting. Approximately $207.6 million five-year-old VLCC versus $139.6 million newbuilding benchmark.
[3] Scorpio Tankers — September 29, 2026 announcement. Two scrubber-fitted Hengli VLCC newbuildings at $135 million each, scheduled for September and October 2028 delivery.
[4] DHT Holdings — October 12, 2026 business update. Q3 VLCC spot TCE of $167,100/day and approximately 50% of Q4 spot days booked at $509,100/day.
[5] DHT Holdings — 2026 disclosures. Three-year charter for the 2015-built DHT Jaguar at $75,000/day and quarterly VLCC earnings history used as market context.
[6] Veson Nautical — September 2026. Rapid expansion in VLCC ordering and orderbook-to-fleet ratio around 38%.
[7] Reuters — September 17, 2026. More than 217 VLCCs commissioned during 2026, more than $20 billion of investment and deliveries extending as far as 2030.
VLCC Premium Payback Calculator
Test how long extraordinary tanker earnings must last to justify paying more for a prompt vessel than a newbuilding. This is intentionally a premium-payback stress test—not a full vessel DCF.